Operating a business comes with a number of challenges, but inventory management is always on top. No doubt, inventory management is a crucial aspect of business profitability. However, many businesses fail to manage their products or materials effectively, which creates chaos and drives more customers away.
In other situations, some businesses overstock and face cash flow issues. In both extremes, effective inventory management strikes a balance. If you’re curious to know how? This blog is going to share tips for smart inventory management to increase business profitability.
1. Prioritize Your Inventory for Inventory Management
When it comes to managing the inventory, the first thing you need to consider is categorizing your inventory into priority groups. This will help you understand the ideal ordering quantities and frequencies.
Along with this, consider determining which items are essential for your business but costing you more money and moving slowly from the inventory. You can categorize your items into A, B, and C groups according to quality and price for effective organization.
2. Track All Product Information
The next thing you should consider is keeping product information for items in your inventory. This information should include the following:
- The SKUs
- Suppliers
- Barcode Data
- Countries of origin
- Lot numbers
Moreover, you might also consider tracking each item’s cost over time. This way, you will be more aware of factors that will affect the pricing, scarcity, and seasonality.
3. Invest In Inventory Management Technology
No wonder every business can handle inventory management with some effort and techniques. However, when it comes to growing your operations, it can be daunting for you to keep track of everything. You might risk spending excessive time on inventory instead of operating your business.
To navigate this challenge, investing in good inventory management software can make tasks easier than ever. Therefore, consider looking for the best software that can help you streamline inventory management, including an order management system.
This way, most of your tasks will be streamlined, and you won’t have to handle these manually.
4. Audit Your Inventory
Some businesses do a comprehensive inventory count once a year, depending on the operations. Others do monthly, weekly, and, in some cases, daily spot checks of their hottest items.
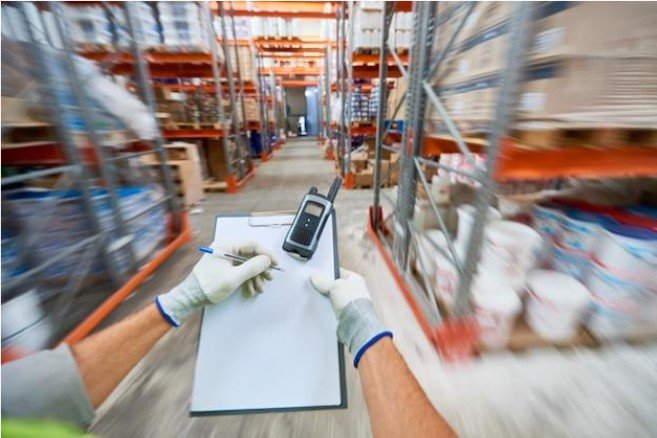
Many businesses are known for doing all the above. So, regardless of how often you do it, it is advised to prioritize the physical counting of your inventory regularly to ensure it matches with what you think you have.
5. Analyze Supplier Performance
An unreliable supplier always creates problems for your inventory. So, if you have suppliers that are habitual in creating troubles for productions or deliveries, this might be time for you to consider taking action on it.
Otherwise, it is advised to discuss the issues with your suppliers to find out what the problem is and be prepared mentally and financially to change partners. This way, you can save yourself from facing uncertain stock levels or the possibility of running out of inventory.
6. Practice the 80/20 Inventory Rule
The 80/30 is the general rule, and it is always beneficial for the business. It states that the 80% of your profit should come from the 20% of your inventory.
You should also understand the sale cycle of your business – including how many you sell in a week or a month. Take some time to monitor them to understand the process closely. These items will make the most money for your business. Therefore, consider managing them correctly to make the most out of them.
7. Be Consistent In Inventory Management
Managing an inventory, regardless of the size, is a bit challenging and taxing. It may seem basic common sense to ensure your team processes incoming inventory. But if there are minor discrepancies, you might end up scratching your head at the end of the month or year.
Therefore, the key pointer you need to assess is how you handle the incoming stock. Do you have a standard process like every other business, or does each employee take a different approach to handling it?
Identify it and use effective training tactics so all the team members receive stocks precisely the same way. Moreover, ensure that all the boxes are verified, received, and unpacked together. Always check for accuracy to eliminate ambiguity.
8. Track Sales for Effective Inventory Management
Last but not least, tracking sales is the key to effective inventory management. It may sound obvious, but effective sales tacking goes beyond adding up money at the end of the day. Therefore, you must learn on a daily basis how many products you sell and how many you need to upgrade your inventory.
You can also analyze your sales data to estimate the success of your products seasonally or as a pair. By understanding the broader picture of how items sell, you can effectively control your inventory and prevent common losses.